Condos are some of the most practical homes around Durango: a place in town you can lock and leave, a ski condo near Purgatory, or a first home that costs less than a house on a lot. But condos come with one financing step that single-family homes don’t have. The lender reviews the whole building and its homeowners association, not just your unit and your credit.
That review is where condo purchases around here most often get surprised late in the process. Here is what lenders look at, why some Durango-area condos are harder to finance than others, and how to find out early.
Why the lender cares about the whole project
When you buy a condo you share walls, roofs, insurance and a budget with your neighbors. If the association is underfunded, tied up in a lawsuit or putting off a major repair, that affects every unit, including yours. So before approving a condo loan, the lender (and whoever buys the loan afterward, often Fannie Mae or Freddie Mac) wants to know the project is sound.
In practice, that means the lender usually asks the HOA or its management company to fill out a condo questionnaire and provide documents such as the budget, the master insurance policy and sometimes meeting minutes or a reserve study. Some HOAs charge a fee for this and some take a week or more to respond, which is one reason I start it early.
What can make a condo hard to finance
Fannie Mae’s guidelines list the kinds of projects it won’t buy loans in. The ones I see come up around Durango and Purgatory are:
- Hotel-style operation. Projects run like a hotel, with things like registration services, daily cleaning, central key systems, required rental pooling, or limits on when owners can use their own unit.
- Big repairs that aren’t funded. Projects that need critical repairs or have significant deferred maintenance, or that have water intrusion or mold problems, are ineligible until the work is done.
- Special assessments tied to those repairs. The lender will ask what an assessment is for and whether the problem has been fixed.
- Pending litigation involving the HOA, especially anything about the building’s safety, structure or habitability. Some minor lawsuits are acceptable.
- One owner holding too many units, or too much of the project used for commercial space.
- Timeshare or fractional ownership.
None of this means a project is a bad place to own. A well-run rental project near the ski area can be a fine investment. It just may not qualify for a standard conventional loan, and you want to know that before you write an offer, not two weeks before closing.
Primary home, second home or rental: it matters
How you’ll use the condo changes the review. Fannie Mae allows a lighter “limited review” for some units in established projects, and it’s available for primary residences, second homes and investment properties, with stricter limits for some of those. New or newer projects usually need a fuller review. If you’re buying a getaway near Purgatory, my second home loans page covers how lenders treat second homes versus rentals.
FHA and VA condo loans
FHA and VA have their own project approval lists. With FHA, the project is either on HUD’s approved list or, in some cases, a single unit can be approved on its own; that takes more paperwork and time, and not every project qualifies. With VA, the project generally needs to be on VA’s approved list before any unit in it can be financed with a VA loan. I check both lists as soon as you have a building in mind.
When a condo doesn’t qualify for a standard loan
Lenders call these “non-warrantable” condos. Depending on the project, there may be options through lenders that offer loans outside Fannie Mae and Freddie Mac guidelines, though the terms are usually different from a standard conventional loan. Because I’m a broker and compare multiple lenders, I can look across programs instead of telling you no because one bank’s guidelines don’t fit. If I can’t find a good option, I’ll tell you that plainly too.
How to avoid a late surprise
- Get pre-approved before you shop, and tell me you’re looking at condos.
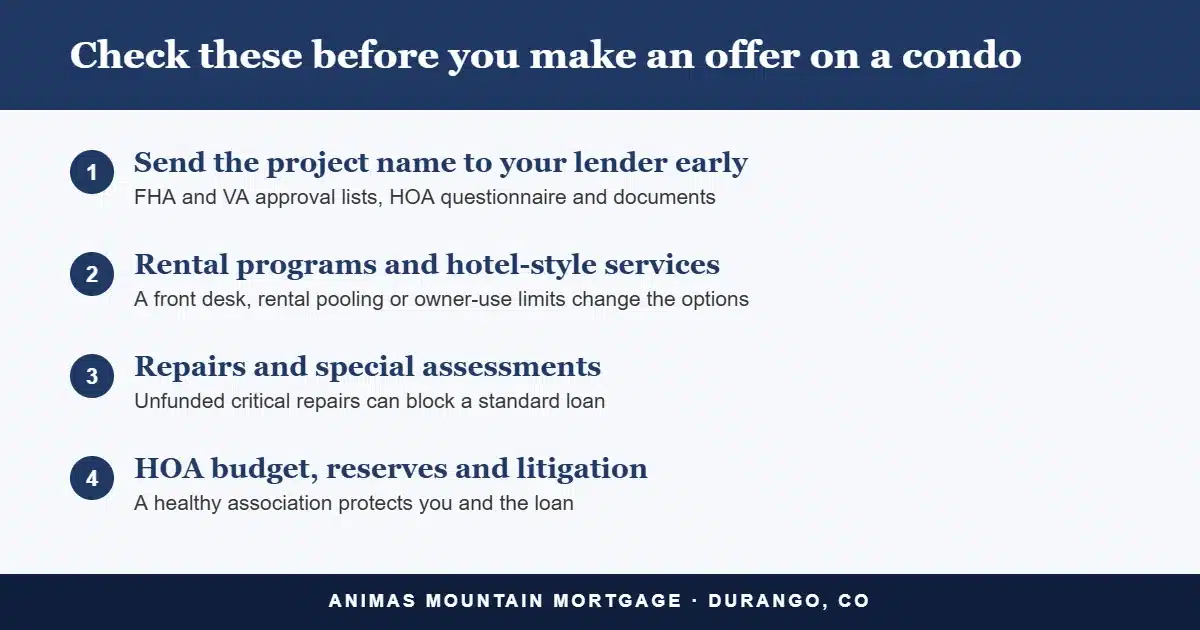
- Send me the project name as soon as you’re interested in a unit. I’ll check the FHA and VA lists and ask what the HOA can provide.
- Ask the listing agent early about special assessments, pending repairs, rental rules and any front desk or rental program.
- Read the HOA budget and reserve information. A healthy reserve fund is good for you as an owner, not just for the lender.
Questions I hear about Durango condos
Can I rent out my condo on a short-term basis?
That depends on the HOA’s rules, local short-term rental rules and how the loan is set up. A unit financed as a second home is meant for your own use, so tell me up front if renting is part of the plan and we’ll structure the loan for that.
Is a ski-area condo harder to finance than one in town?
Not always, but resort projects are more likely to have rental programs or hotel-style services that lenders treat differently. It comes down to the specific project.
Do townhomes go through the same review?
Often not. Many townhomes are part of a planned unit development (PUD) rather than a condo, and those usually don’t need the same project review. The legal documents decide which one it is, and I’ll check.
Let’s check the building before you fall in love with it
If you’re looking at a condo in Durango, Purgatory or anywhere around La Plata County, call or text me at 970-828-1610 or reach out through my contact page. Send me the project name and I’ll tell you what we’re likely to run into. You can also read more about how I work as a local Durango mortgage broker.
Peter Pritchard
Not affiliated with or endorsed by the U.S. Department of Veterans Affairs or HUD.
This article is for general information only and is not financial or legal advice. Loan programs, terms and availability vary.
Peter Pritchard NMLS #404172 | Animas Mountain Mortgage Inc. NMLS #1742747 | Equal Housing Opportunity. All loans subject to credit approval.
All Newsletters
SEE MOREFedWatch Update: Navigating the Federal Reserve’s Monetary Policy February 8, 2024
The Fed’s campaign of interest rate hikes spanned over 18 months, representing a significant intervention in the central bank’s history. These measures have transitioned the Fed into a phase of observation, as it awaits indications of declining inflation rates towards its 2% target, as measured by the Personal Consumption Expenditure (PCE) index, a preferred inflation gauge.
When should you Refinance? February 1, 2024
When should I refinance?
Fed Watch December 13, 2022
So that’s my goal here – to shed some light on what the Federal Reserve is and how it impacts your finances and investments.
Buying a Second Home in Durango: What to Know Before You Shop October 17, 2026
Thinking about a cabin near Purgatory, a place at Vallecito or a condo in town? Here is how second-home financing works and what to check before you make an offer.
Buying a Mountain or Rural Home Near Durango: Wells, Septic, Roads and Insurance October 17, 2026
A lot of the homes people fall in love with around Durango aren’t on a city street. They’re up a county road in the Animas Valley, on a few acres outside Bayfield or Hesperus, or tucked in the trees near Vallecito. These homes finance just fine most of the time, but they come with a …
USDA Home Loans Near Durango: Eligibility in Bayfield, Ignacio and Rural La Plata County October 15, 2026
If you’re house hunting around Bayfield, Ignacio or out on one of La Plata County’s rural roads, there’s a loan program you should at least check before you decide how to finance: the USDA Guaranteed home loan. A lot of buyers I talk to assume “USDA” means farms only. It doesn’t. It’s a mainstream home …