If you’re house hunting around Bayfield, Ignacio or out on one of La Plata County’s rural roads, there’s a loan program you should at least check before you decide how to finance: the USDA Guaranteed home loan. A lot of buyers I talk to assume “USDA” means farms only. It doesn’t. It’s a mainstream home loan for primary residences in eligible rural areas, and parts of our county may qualify.
I’ve been a mortgage originator for 28 years, and like a broker I shop multiple lenders. Here’s how I explain USDA loans to local buyers, including where they shine and where they don’t fit.
Photo: Morgan Newnham / Unsplash
What a USDA Guaranteed loan is
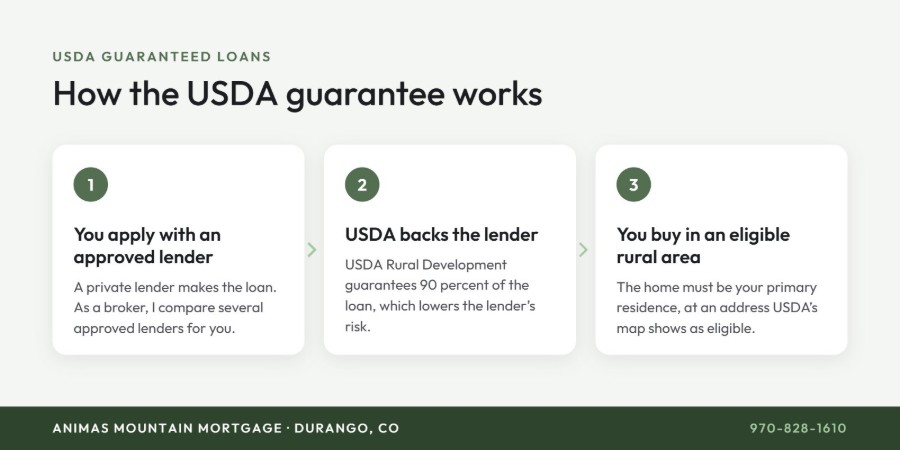
The program is formally the USDA Rural Development Single Family Housing Guaranteed Loan Program. USDA doesn’t lend the money itself. You borrow from an approved private lender, and USDA guarantees 90 percent of the loan, which lowers the lender’s risk. That guarantee is what makes the program attractive for buyers who don’t have a large pile of cash saved.
There’s a cost to that guarantee: a one-time upfront guarantee fee (which can usually be financed into the loan) and an annual fee that’s collected as part of your monthly payment. I’ll always show you those fees side by side with FHA and conventional options so you can compare honestly.
The four eligibility tests
1. The property has to be in an eligible rural area
Eligibility is decided address by address using USDA’s property eligibility map, not by town name or ZIP code. Two homes a few miles apart can land on different sides of a boundary, and USDA updates its maps from time to time. That’s why I check the exact address before anyone gets their heart set on USDA financing. If you’re looking around Bayfield, Ignacio, Hesperus or elsewhere outside Durango, send me the address and I’ll check it.
2. Household income has to fit the limit
Your household income can’t exceed 115 percent of the area’s median household income. The part that surprises people: USDA counts the income of all adults in the household, not just the people on the loan. A working adult child or a roommate living with you can push a household over the limit even if they’re not borrowing. Household size also matters, since larger households get a higher limit.
3. It has to be your primary residence
USDA loans are for the home you’ll live in. They can’t be used for a second home, a vacation cabin or a rental. If that’s your plan, a second home loan or an investment property loan is the better route.
4. You have to qualify to repay
There’s no maximum purchase price in the program. Instead, how much you can borrow depends on your ability to repay: income, debts and credit. The home also has to meet basic standards for safety and condition.
Rural La Plata County issues to plan for
The homes that tend to fall in eligible areas are also the ones with country-property quirks. A few things I see come up:
- Wells and septic. Lenders and appraisers may ask for water and septic testing or inspections. Order these early so a surprise doesn’t push your closing date.
- Acreage and outbuildings. USDA is for a home, not an income-producing farm or ranch. Properties with extra land or agricultural use need a careful look before you write an offer.
- Manufactured homes. Rules for manufactured homes are stricter than for site-built homes, so ask me before you fall for one.
- Condos. A condo generally needs to be approved or accepted by HUD/FHA, VA, Fannie Mae or Freddie Mac.
- Wildfire insurance. Homeowners insurance in wooded areas can take longer to place. Start getting quotes as soon as you’re under contract.
Photo: Tyler Delgado / Unsplash
The honest trade-offs
USDA isn’t automatically the right answer. The guarantee fees add cost, the income limit rules out some households, and the property and location rules narrow which homes you can buy. Depending on your credit and savings, an FHA loan or a conventional loan may cost less over time or give you more flexibility. Veterans should also compare a VA loan. My job is to put the options next to each other and tell you which one makes the most sense, even if it’s not the one you walked in asking about.
Photo: Laura Seaman / Unsplash
How I’d get started
- Send me the address (or the area you’re shopping) so I can check property eligibility.
- Tell me who lives in the household and their incomes so we can check the income limit.
- Get pre-approved so you know your real budget before you make offers.
- Line up inspections, well and septic testing, and insurance quotes as soon as you’re under contract.
You can read more on my USDA loans page.
Frequently asked questions
Is all of La Plata County eligible for USDA loans?
No. Eligibility is set by USDA’s map and checked address by address. Some areas qualify and others don’t, and the maps can change. The only reliable answer comes from checking the specific property, which I’m glad to do.
Do I have to be a first-time buyer to use a USDA loan?
No. USDA Guaranteed loans aren’t limited to first-time buyers. You need to meet the income, property, occupancy and repayment requirements, and the home has to be your primary residence.
Can I use a USDA loan to refinance?
Only if your current loan is already a USDA Rural Development loan. If you have another type of mortgage, we’d look at conventional, FHA or VA refinance options instead.
Let’s check your address
If you’re buying outside Durango and wondering whether USDA could work, call or text me at 970-828-1610 or reach out through my contact page. I’ll check the property and your household income against USDA’s guidelines and give you a straight answer, along with how it compares to your other options.
Peter Pritchard
Sources: USDA Rural Development, Single Family Housing Guaranteed Loan Program fact sheet and program overview (rd.usda.gov).
This article is for general information only and is not financial or legal advice. Loan programs, terms and availability vary.
Peter Pritchard NMLS #404172 | Animas Mountain Mortgage Inc. NMLS #1742747 | Equal Housing Opportunity. All loans subject to credit approval.
Header photo: “Cattle grazing in Bayfield, Colorado” by TheFirstMotion, CC BY-SA 4.0, cropped.
All Articles
SEE MOREBuying a Home in Durango This Winter: A Local Lender’s Checklist November 4, 2026
Six things to plan for when you buy a home in Durango between November and March, from pre-approval timing to snowy inspections and holiday closings.
Buying a Duplex in Durango: Live in One Unit, Rent the Others November 1, 2026
You can buy a duplex, triplex or fourplex in Durango, live in one unit and rent the others, and finance it as your own home. Here is how FHA, VA and conventional loans work for it, the LLC question, and what to check in La Plata County.
Fixer-Upper Loans in Durango: FHA 203(k) vs. Fannie Mae HomeStyle October 26, 2026
You can buy a home that needs work and finance the repairs in the same loan. Here is how FHA 203(k) and Fannie Mae HomeStyle renovation loans work in Durango and Southwest Colorado, and which one fits.